 12 min read
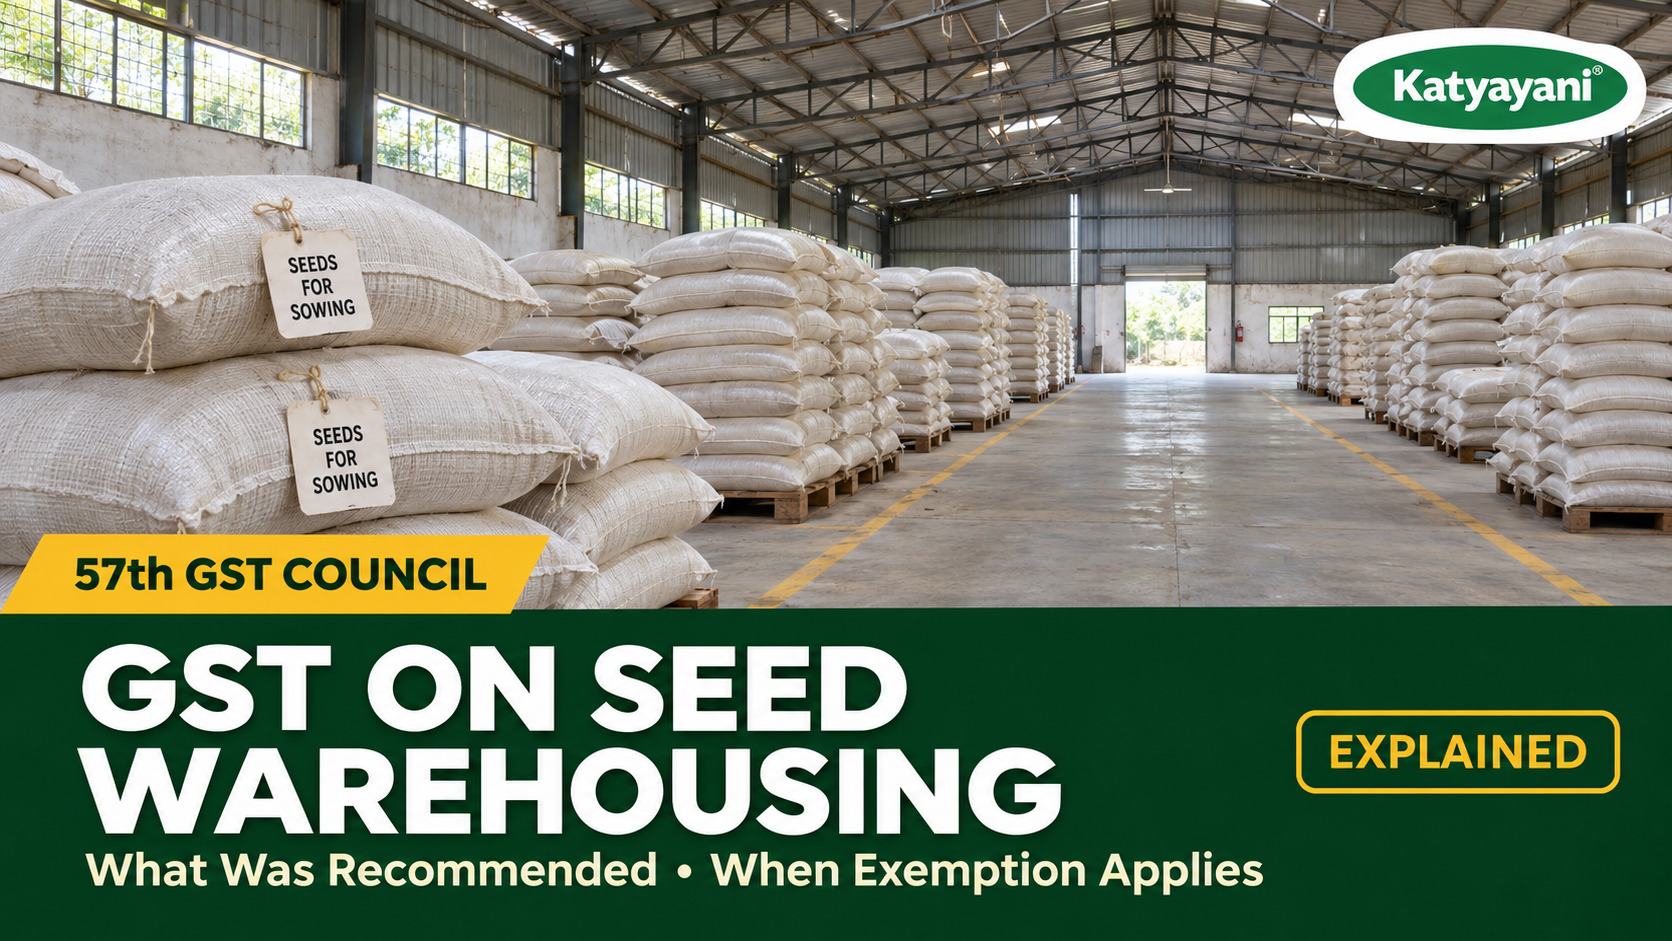
On 8 October 2026 the 57th GST Council meeting recommended exempting from GST "the services by way of storage or warehousing of seeds meant for sowing" (PIB, 8 Oct 2026). PIB states that recommendations take effect through circulars, notifications or law amendments, which alone have the force of law. The exemption therefore applies from the date written in the CBIC notification, which is published on taxinformation.cbic.gov.in. The item covers a service, storage or warehousing of seeds meant for sowing. It does not cover the sale of seed.
What did the 57th GST Council recommend on GST for seed warehousing?
On 8 October 2026 the 57th GST Council meeting in New Delhi recommended exempting from GST "the services by way of storage or warehousing of seeds meant for sowing". The PIB release lists it as item 6 under "Recommendations relating to services". In plain words, the Council wants the storage charge for sowing seed to carry no GST once the rule is notified.
The PIB release of 8 Oct 2026 says the meeting was chaired by the Union Finance Minister. It also says the 56th meeting a year earlier focused on lower and simpler rates, while the 57th mainly recommended process reforms for registration, returns, refunds and adjudication, plus clarifications on how GST applies to certain goods and services.
The seed item sits next to a similar one. Item 7 recommends exempting the "agricultural support services of curing coffee provided by the coffee curers to the cultivators". Both are services, not goods. Nothing in the release changes the GST rate on seed itself.
Here is why a short line matters. Think of a seed company that buys certified wheat seed from growers in March and keeps it in a hired warehouse until the sowing window opens in October. For months it pays a storage charge. If that charge carries GST that the company cannot recover, the tax becomes a cost inside the price of every bag. The Council item is aimed at that kind of cost.
How does the seed warehousing recommendation become law?
A Council recommendation becomes law through a CBIC notification. The PIB release says the recommendations are presented "in simple language for information of the stakeholders" and will be given effect "through the relevant circulars/ notifications/ law amendments which alone shall have the force of law". The exemption applies from the date written in the notification.
The notification number, the exact entry wording and the "comes into force" date are published by CBIC. Read them on the CBIC tax information portal or in the notifications list on the CBIC GST site. Use that date in your books, not the date of the Council meeting.
| Step | What it is | Source and date |
|---|---|---|
| 1. Council meeting | The GST Council discusses and recommends | 57th meeting, 8 Oct 2026 (PIB) |
| 2. PIB release | Ministry of Finance lists the recommendations in simple language | PIB release, 8 Oct 2026 |
| 3. CBIC notification | A numbered notification in the Gazette gives the legal text and the start date | Published on taxinformation.cbic.gov.in and cbic-gst.gov.in |
| 4. Circular or FAQ | CBIC explains grey areas | PIB says FAQs are being issued to clarify doubts |
In short, apply the exemption in an invoice from the date given in the notification. A tax professional can tell you how the rule applies to your own agreement.
What is the GST Council, and what is Article 279A?
The GST Council is the body created under Article 279A of the Constitution to recommend GST rules to the Union and the States. Its recommendations cover which goods and services are taxed or exempt, GST rates and place of supply rules. Its decisions reach the public only through notifications and circulars.
The GST Council About page explains the set-up. Under Article 279A(2) the members are the Union Finance Minister, the Union Minister of State in charge of Revenue or Finance, and the minister in charge of finance or taxation (or another minister nominated) from each State Government. The notification bringing Article 279A into force, with effect from 12 September 2016, was issued on 10 September 2016.
The page also explains how decisions are made. The Council generally decides by consensus. If a proposal goes to a vote, the Central Government carries one-third of the votes cast and all State Governments together carry two-thirds, and a proposal is carried if the weighted votes in favour are three-fourths or more. That is why a Council decision is a joint Union and State decision, not an order of one ministry.
The PIB release of 8 Oct 2026 names who attended the 57th meeting: Chief Ministers of Delhi, Goa, Haryana, Jammu and Kashmir, Karnataka, Kerala, Maharashtra and Meghalaya, Deputy Chief Ministers of Manipur and Telangana, and finance ministers and senior members of other States and Union Territories with a Legislative Assembly.
Is warehousing service subject to GST?
A warehouse charge is a payment for a service, and a service is taxed under GST unless a notification exempts it. Exemptions for services are listed in Notification 12/2017-Central Tax (Rate), issued under section 11(1) of the CGST Act. So the answer depends on what you store and which exemption entry fits it.
The original CBIC text of Notification 12/2017-Central Tax (Rate), dated 28 June 2017, shows how this works for farm produce. Serial number 54 exempts, at a nil rate, services relating to cultivation of plants and rearing of animals, and item (e) of that entry reads "loading, unloading, packing, storage or warehousing of agricultural produce". In the same notification, "agricultural produce" means produce of cultivation of plants and rearing of animals, except horses, for food, fibre, fuel, raw material or similar products, with either no processing or only the processing usually done by a cultivator or producer that does not alter its essential characteristics but makes it marketable for the primary market.
Two points to remember. First, that is the original 2017 text. The notification has been amended many times since, and serial numbers and wording can change, so read the current consolidated version on the CBIC portal before quoting any entry. Second, how an entry treats packed or treated seed depends on its exact wording, so ask a tax professional about a given product.
| Question | Short answer | Where it comes from |
|---|---|---|
| Is a warehouse charge a service? | Yes, it is a payment for storage service | Notification 12/2017-CT(R) exempts "services", issued under section 11(1) CGST Act (CBIC original text) |
| Does GST apply by default? | Yes, unless an exemption entry covers the service | Same notification: exemption applies to services "of description as specified" in its table |
| Is storing agricultural produce exempt? | Yes, under serial 54(e) of the original notification, if the goods are agricultural produce as defined | CBIC, 28 Jun 2017 text |
| Is storing seeds meant for sowing exempt now? | Recommended on 8 Oct 2026; it applies from the date given in the CBIC notification | PIB, 8 Oct 2026 |
What exactly does the PIB release say about seeds meant for sowing?
The PIB release records the Council recommendation "to exempt from GST, the services by way of storage or warehousing of seeds meant for sowing". The legal wording, the meaning of "seed" for this entry and the date from which it applies are written in the CBIC notification that gives effect to the recommendation.
| Detail | What the PIB release of 8 Oct 2026 states | What this means for you |
|---|---|---|
| Storage or warehousing of seeds meant for sowing | Item 6 of C2: recommended for exemption from GST | This is the recommended exemption |
| Type of supply | A service: storage or warehousing | The item is about a service, not about goods |
| Purpose of the seed | "Meant for sowing" | The purpose decides, not how the seed looks |
| Legal wording and meaning of "seed" | Given in the CBIC notification | Read the notification text before assuming that a product counts as seed |
| Date from which it applies | Written in the notification as "comes into force" | Apply the exemption from that date, not from the meeting date |
| Notification number | Shown on the CBIC notification | Search the CBIC notifications list by subject |
| Transport, testing, grading or packing of seed | Separate services | Check each against the notification text |
Two small words in the recommendation carry the weight. "Storage or warehousing" is the service. "Meant for sowing" is the purpose. The same bag of wheat can be seed for one buyer and flour for another, so the words point to what the goods are for, not how they look. How the final notification applies that purpose test is what to read for when it appears.
Which services does the recommendation cover, and what stays outside it?
On the PIB wording, one activity is covered: storage or warehousing of seeds meant for sowing. The sale of seed, transport, testing, grading, packing and hiring out an empty godown are different supplies. Check each of them against the final notification text.
- Covered by the recommendation: the service of storage or warehousing of seeds meant for sowing.
- Separate supply: the sale of seed. The recommendation is about a service, not about goods.
- Separate supply: transport of seed, which is its own service.
- Separate supply: seed testing, grading, treatment or packing done as separate services.
- Separate supply: renting an empty godown. A pure lease of space and a storage service can be different things, so keep the description in your agreement clear.
- Outside the purpose words: seed bought for food, feed or industrial use. The words are "meant for sowing".
A short example. A seed company pays one warehouse a single monthly bill that adds up three things: shelf space for 800 tonnes of seed, a charge for opening and re-stacking bags, and a transport run to a dealer. The first line is storage of seed. The other two are different services. A bill that names each service on its own line makes it much easier to see which line an exemption could reach.
Who may be affected by the seed storage recommendation?
Anyone who pays or charges for storing seed may be affected: seed companies, FPOs that produce seed, cold stores holding seed tubers, nurseries, distributors and warehouse operators. The list below is a reading of the wording of the recommendation. A farmer benefits only if the storage cost shows up in the seed price.
- Seed companies: they hold seed in bulk between harvest and sowing, so storage is a regular cost for them.
- FPOs that produce seed: a farmers' group that stores seed before distribution should watch the notification. See the SHG vs FPO guide for how such groups are set up.
- Warehouse and cold store operators: they will need the exact entry to quote on invoices once it is notified.
- Input dealers: dealers who hold seed stock near the sowing window can read the rabi stock list for dealers together with the storage and compliance checks there.
- Farmers: the recommendation concerns a storage service. It does not change the GST rate on seed.
How is this different from the farm-input GST cuts of September 2025?
The September 2025 decisions, from the 56th meeting, were rate cuts on goods: tractors, listed farm machinery, listed bio-pesticides and FCO-registered micronutrients moved from 12% to 5%. The October 2026 seed storage item is a services exemption, not a rate cut. It would remove tax on one service and does not touch the rate on seed or any input.
The PIB release of 3 Sep 2025 lists a reduction from 12% to 5% on agricultural goods such as tractors and farm machinery for soil preparation, harvesting or threshing, including balers, mowers and composting machines. It also lists micronutrients covered under serial number 1(g) of Schedule 1, Part (A) of the Fertilizer Control Order, 1985 and made by manufacturers registered under that Order, and a list of bio-pesticides from 12% to 5%. That list includes Bacillus thuringiensis types, Trichoderma viride, Trichoderma harzianum, Pseudomonas fluorescens, Beauveria bassiana, NPVs of Helicoverpa armigera and Spodoptera litura, and neem based pesticides. The release also cuts GST on sulphuric acid, nitric acid and ammonia from 18% to 5% to correct an inverted duty structure in the fertilizer sector.
The live post on GST on tractors and farm machinery walks through the machinery side, so this post does not repeat it. The point to keep in mind is simple. A rate cut lowers the tax on a product you buy. An exemption removes tax from a service you buy. They are different tools for different costs.
What else did the 57th meeting recommend that matters to farm-input businesses?
Besides seed storage, the PIB release of 8 Oct 2026 has a few farm-related items: a nil rate for psyllium seeds, a clarification that registered seaweed-extract biostimulants are fertilisers under heading 3101, a rate alignment for re-treaded tractor tyres, the coffee curing exemption and a 5% rate for some delivery services supplied through e-commerce operators.
| Item in the PIB release | What it says | Who should read it |
|---|---|---|
| Psyllium seeds (isabgol) | Nil rate of GST, whether the seeds are fresh, chilled, frozen or dried (goods, C1 item 6) | Growers and traders of isabgol |
| Seaweed-extract biostimulants | Those registered under Schedule VI to the Fertiliser (Inorganic, Organic or Mixed) (Control) Order, 1985 are classifiable under heading 3101 as fertilisers; past cases regularised "as is where is" (C1 item 3) | Biostimulant makers and dealers |
| Re-treaded tractor tyres | GST rate aligned with the rate on new tractor tyres to correct an anomaly (C1 item 7) | Tractor owners, tyre dealers |
| Coffee curing | Agricultural support services of curing coffee, provided by coffee curers to cultivators, to be exempt (C2 item 7) | Coffee growers, curing works |
| E-commerce delivery services | GST rate of 5% without ITC for delivery services supplied through an e-commerce operator (C2 item 2) | Online sellers, delivery partners |
| Waste and scrap | Waste and scrap of plastics, electronics, tyres and used cooking oil brought under reverse charge when supplied by an unregistered to a registered person; 2% TDS on supply from a registered to a registered person (C1 item 5) | Businesses that sell scrap |
If you work with biostimulants, the live post on biostimulant manufacturer rules under FCO explains what Schedule VI registration means. The PIB item above is about the GST heading for such products, not about whether a product is registered.
What did the 57th meeting recommend on refunds, exports and zero-rated supplies?
The PIB release recommends faster, system-based refunds. In Phase 1, 90% of a refund claim for zero-rated supplies and inverted duty structure would be sanctioned provisionally by the system, without officer intervention, on a risk basis. These are recommendations that need amendments to the CGST Act and Rules. They apply to exporters of any product.
The release places these items under "Reforms relating to exports/zero rating of supplies of goods and services". Here is what the release states, in its own order.
- Provisional refund (Phase 1): 90% of the amount claimed for zero-rated supplies and inverted duty structure is sanctioned provisionally by the system, without officer intervention, on the basis of risk identification.
- Full refund in Phase 2: after system-based acknowledgement, automated sanction of the full refund claim for zero-rated supplies, after adjusting pending dues.
- Faster acknowledgement: the time limit for an acknowledgement or deficiency memo to fall from 15 days to 10 days, with a deemed acknowledgement if the officer does not act within 10 days.
- No 1.5 times limit: amendment of rule 89(4)(C) of the CGST Rules to remove the restriction that caps the turnover of zero-rated supply of goods at 1.5 times the value of like goods supplied domestically.
- Input services credit: refund of accumulated ITC on input services in inverted duty cases, for ITC availed on or after 1 November 2026.
- Capital goods credit: refund of ITC on capital goods spread over 60 months, for ITC availed on or after 1 April 2027, in zero-rated and inverted duty cases.
- Delivery in an SEZ or FTWZ: a new explanation in section 16(1) of the IGST Act so that goods supplied to an overseas buyer but delivered in an SEZ or free trade warehousing zone, with payment in convertible foreign exchange or in Indian rupees where the RBI permits, count as a supply to an SEZ or FTWZ.
Watch the date in the input services line. The date 1 November 2026 belongs to the refund of input service credit in inverted duty cases. It is not a date for seed storage, and it should not be copied across.
For an exporter the practical meaning is working capital: money held in unclaimed credit could come back sooner once the law and rules are changed. Until then, claim refunds under the rules that apply to you today. If you are new to exporting, the live posts on the IEC code for agri exporters and APEDA registration and RCMC explain the registrations that come first.
Which registration, return and penalty changes could affect a small seed or input business?
The PIB release recommends several process changes that matter to a small business even though they are not about seed. They include simpler registration, automatic acceptance of amendments to registration details, waiver of late fee for small taxpayers, a higher prosecution threshold and a lower general penalty. All are recommendations that need law or rule changes.
| Area | What the PIB release recommends (8 Oct 2026) | Section of release |
|---|---|---|
| Registration documents | A circular with FAQs listing documents and information needed; drop boxes in FORM GST REG-01 so applicants and officers see what is required | A1, item 1 |
| Changes to registration details | Automatic acceptance of amendments to all registration particulars except the principal place of business; for the automatic route under rule 14A, including the principal place of business | A1, item 2 |
| Cancellation of registration | Applications in FORM GST REG-16 accepted automatically once pending returns are filed and dues paid, in two phases | A1, item 3 |
| Small sellers on e-commerce platforms | New rule 14B so a small supplier who intends to pass on not more than Rs. 2.5 lakh of ITC a month can register in a State by declaring the e-commerce operator's warehouse there as the principal place of business | A1, item 4 |
| Late fee relief | Waiver of late fee on delayed return under section 39(1) for taxpayers with turnover up to Rs. 5 crore in the preceding year, if the return is filed by the end of the month in which it was due | B3, item 15 |
| Prosecution threshold | Raised from Rs. 1 crore to Rs. 5 crore | B3, item 11 |
| Return mismatches | New facilities such as the Electronic Credit Reversal and Reclaim Statement; recommended for the return of April 2027 | A2, item 5 |
| Blocked credit | Section 17(5) amended to remove restrictions on ITC for items such as outdoor catering, health and life insurance, telecommunication towers and goods written off on expiry of shelf life as required by law | B1, item 9 |
The line about goods written off on expiry of shelf life is worth a second look for dealers of pesticides, fertilisers and seed, who often hold dated stock. The release words it as removing the restriction on ITC for "goods destroyed or written off on expiry of shelf life as required by law". It is a recommendation for an amendment to section 17(5), so keep claiming credit under the rule that applies to you today.
The release also recommends an optional Annual Return Quarterly Payment scheme in principle, for taxpayers with turnover up to Rs. 5 crore who make supplies only to unregistered persons. An agri input shop selling to farmers who are not registered would want to read the final scheme, if it is notified, to see whether its sales pattern fits.
Which items are exempted from GST in 2026, and what are the "10 exemptions" people ask about?
There is no fixed list of ten. GST exemptions are spread across several notifications and change over time. The PIB release of 8 Oct 2026 recommends a handful of new service exemptions, listed below. They are recommendations until notified, so check each against the CBIC notifications list before you rely on it.
| Item recommended for exemption | PIB release reference | Status |
|---|---|---|
| Storage or warehousing of seeds meant for sowing | C2, item 6 | Recommendation |
| Curing of coffee by coffee curers for cultivators | C2, item 7 | Recommendation |
| Passenger transport by helicopter on seat-sharing basis from or to airports or helipads in north-eastern States, Sikkim and Bagdogra in West Bengal | C2, item 5 | Recommendation |
| Services of the Seamen's Provident Fund Organisation to persons governed by the Seamen's Provident Fund Act, 1966 | C2, item 8 | Recommendation |
| Import of services by an establishment of a foreign shipping company in India from a related person or its establishment outside India, when made without consideration | C2, item 10 | Recommendation |
| Grant of exclusive right, licence and authority to collect toll fee to the concessionaire for highway projects (upfront or concession amount under the Toll Operate Transfer model) | C2, item 11 | Recommendation |
| Psyllium seeds (isabgol): nil rate of GST | C1, item 6 | Recommendation |
Keep the two kinds of item apart. The psyllium line is a goods rate decision. The others are services. If you search for "which items are exempted from GST", check the date of the page. A list from 2024 will miss all of these, and a list that gives a start date should name the notification it comes from.
What should a seed business or warehouse do now?
Check three things: the exact notification, your own paperwork and your invoice lines. Look for the notification on the CBIC portal, compare your storage agreements with the words "storage or warehousing of seeds meant for sowing", and make sure each service on a bill is named separately. These steps cost nothing and prevent most disputes later.
- Search the CBIC notifications list and the tax information portal for the Central Tax (Rate) notification that gives effect to item 6 of section C2. Note its number, date and "comes into force" line. The exemption applies from that date.
- List what you store. Mark which lots are seed meant for sowing and which are grain or produce meant for food or processing. Different rules may apply to the second group.
- Read your storage agreements. Does each describe storage of goods, or does it describe leasing space? Keep the description honest and clear.
- Ask the warehouse to split its bill into separate lines: storage, handling, transport and any testing or treatment.
- If your seed or your warehouse crosses a state border, also look for the matching Integrated Tax notification on the CBIC portal.
- Keep the PIB release of 8 Oct 2026 and the notification together once you have it. If a circular or FAQ follows, add it to the same file.
If you run an input shop that stocks seed along with fertilisers and pesticides, the same discipline helps with other paperwork. The live posts on seed dealer licence renewal and dealer licence rules cover the licences, and the agri input shop business plan covers the running costs that a storage exemption could touch.
What mistakes do people make when they read GST news like this?
The most common mistake is treating a Council recommendation as law. The second is applying a services exemption to goods. A third is copying a start date from a news page. Reading the notification itself, not a headline, avoids all three, and so does checking the date on every page you rely on.
- Recommendation read as law: headlines of 8 Oct 2026 said the Council "exempts" or "approves". The PIB note says only notifications, circulars or law amendments have the force of law.
- Meeting date taken as start date: 8 Oct 2026 is the date of the meeting, not the date from which a tax rule applies.
- Wrong date copied across items: 1 November 2026 and 1 April 2027 in the PIB release belong to refund items, not to seed storage.
- Services exemption applied to the sale of seed: the recommendation is about storage or warehousing, not about goods.
- Sowing purpose ignored: seed bought for food, feed or industrial use is outside the words "meant for sowing".
- One bill for everything: a single lump-sum bill makes it impossible to see which line could be exempt.
- Commentary used as the rule: news and tax commentary help you find a notification, but the notification on the CBIC portal is the rule.
How can you track a GST Council recommendation until it becomes law?
Follow four steps: the Council meeting, the PIB press release, the CBIC notification and the start date written inside it. A decision becomes law only with the notification. Check PIB on meeting day, then the GST Council and CBIC sites over the following weeks, and read the "comes into force" line in the notification.
- Meeting day: the Ministry of Finance issues a PIB press release, such as the one of 8 Oct 2026, that lists the recommendations in simple language.
- Council site: the GST Council website keeps meeting details. The PIB release of 8 Oct 2026 said FAQs were being issued.
- CBIC notification: rate and exemption changes arrive as numbered notifications on the CBIC GST portal (see the list of Central Tax (Rate) notifications), each with a date. Search by subject, such as "storage or warehousing of seeds".
- Start date: read the line "comes into force" or "with effect from" inside the notification. The meeting date and the notification date are different dates.
- Circulars and FAQs: CBIC may later issue a circular that explains grey areas. Add it to your file when it appears.
For other scheme dates in one place, the agriculture schemes calendar is a good companion. For credit linked to stored produce, the live post on the e-NWR loan against a warehouse receipt explains how a farmer can borrow against crops kept in a registered warehouse. That is a different topic from tax, but both come up when a farm business plans storage.
Conclusion
The 57th GST Council meeting recommended on 8 October 2026 to exempt from GST the services by way of storage or warehousing of seeds meant for sowing (PIB, 8 Oct 2026). PIB says recommendations take effect through notifications, circulars or law amendments, which alone carry the force of law. The exemption applies from the date written in the CBIC notification, published on taxinformation.cbic.gov.in. The item names a service, not the sale of seed. Open the notification, read its start date, and split your storage bills line by line.
Leave a Comment